The phone rings a few days after your accident. It is a claims adjuster from the at-fault driver’s insurance company. They sound reasonable and sympathetic. They tell you they want to resolve your claim quickly, and they have an offer ready. It sounds like real money, and settling now would make the whole ordeal go away.
In almost every case, the answer to whether you should accept that offer is no. Not because the insurance company is necessarily acting in bad faith, but because of a structural reality: at the moment they call, they know far less about the full extent of your damages than they will in three or six months. And the offer reflects what is easiest and cheapest for them right now, not what your case is actually worth.
Why Insurance Companies Make Early Offers
Insurance companies are businesses. Their financial interest is in resolving claims for as little as possible, as quickly as possible. An early settlement offer serves both goals. When you accept an early offer, you are settling before the full picture of your injuries is known, before your medical treatment is complete, and before you have had time to consult with an attorney who can evaluate the full value of your claim.
Early offers are almost universally lower than what a fully developed case would produce for several reasons. The insurer does not yet know whether your injuries will require surgery, long-term therapy, or specialist care. They have not seen your complete medical records. They do not know how the injury will affect your ability to work in six months. And they are betting that the stress, the bills, and the inconvenience of the situation will make a quick resolution attractive before you understand what you are giving up.
What Happens When You Accept a Settlement
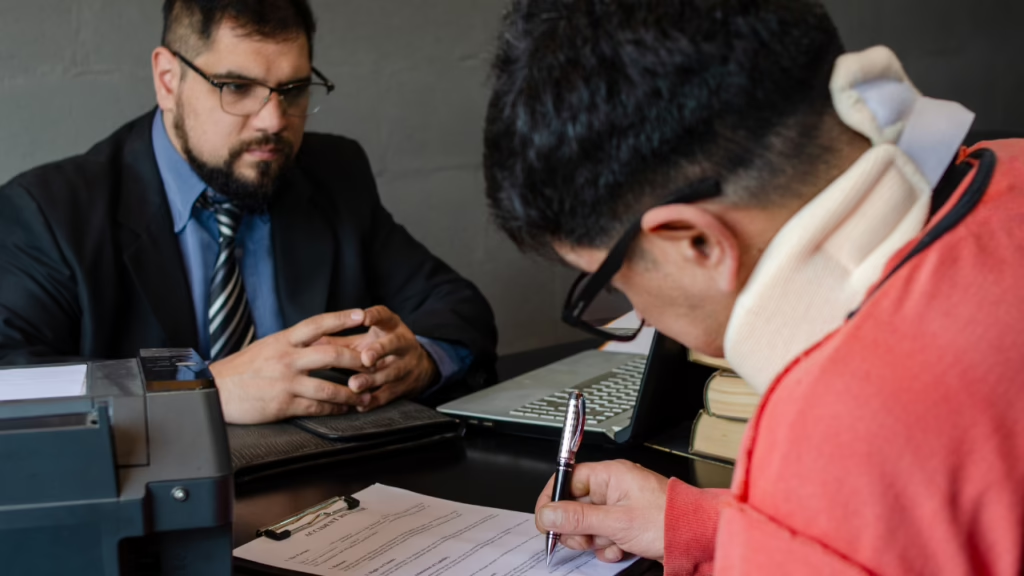
A personal injury settlement requires you to sign a release. The release is a legal document that permanently and completely extinguishes your claim against the at-fault party and their insurer in exchange for the settlement payment. Once signed, the release cannot be undone.
This is the critical point: if you settle for $8,000 today and discover three months from now that you need spinal surgery costing $60,000, you have no recourse. The release you signed bars any further claim. The insurer will not reopen the claim. The at-fault driver is protected. You absorb the cost of whatever your settlement did not cover.
A signed release is permanent. The most important reason not to accept an early settlement offer is that you may not yet know what your injuries will actually cost.
The Maximum Medical Improvement Standard
The appropriate time to evaluate a settlement offer is after you have reached maximum medical improvement, often abbreviated as MMI. This is the point at which your treating physicians have determined you have recovered as fully as you are expected to, and they can assess what, if any, ongoing or future medical needs remain.
Settling before MMI means settling before the full cost of your care is known. It means settling before you know whether you will need additional procedures. It means settling before your doctor can provide a prognosis about permanent limitations, chronic pain, or future treatment requirements. All of those unknowns translate directly into undercompensation when they are not accounted for in the settlement.
In some cases, reaching MMI takes months. In serious injury cases involving surgery, rehabilitation, and specialist care, it can take a year or more. This is why the pressure to settle quickly is particularly dangerous in serious injury cases, where the long-term cost profile is most uncertain in the immediate aftermath of the accident.
What a Fair Settlement Should Include
A fully developed personal injury settlement in Nevada accounts for all of the following categories of damages:
- All past medical expenses from the date of the accident through the settlement date
- All future medical expenses projected over the remainder of the treatment need, calculated with expert input in serious cases
- All past lost wages from the time of the accident through the settlement date
- Reduced future earning capacity if the injury has permanently limited the ability to perform prior work
- Pain and suffering from the date of injury through recovery or for life in the case of permanent injuries
- Emotional distress and its documented impact on daily functioning
- Loss of enjoyment of life covering activities, hobbies, and relationships affected by the injury
- Property damage to the vehicle and personal property
A first-call settlement offer from an insurance adjuster typically reflects only a fraction of these categories, weighted heavily toward the known medical bills at the time of the call. Future damages, non-economic damages, and long-term impact are systematically underrepresented in early offers.
How to Respond to a First Settlement Offer
When an insurer contacts you with an early offer, you are not obligated to accept, reject, or counter immediately. You are entitled to time to evaluate the offer. Several steps are appropriate:
- Do not give a recorded statement to the adjuster during the call or accept the offer verbally.
- Write down the offer amount, the name of the adjuster, and the date of the call.
- Tell the adjuster you are consulting with an attorney before making any decisions.
- Contact a Nevada personal injury attorney as soon as possible. Many will evaluate the offer and your case in a free consultation.
An attorney can assess whether the offer reflects the real value of your claim, identify categories of damages that are not reflected in the offer, advise you on the likely trajectory of the case if you pursue full compensation, and handle all further communications with the insurer on your behalf.
What If I Cannot Afford to Wait?
This is a real concern for many injury victims, particularly when medical bills are accumulating and income has been disrupted. Several mechanisms exist to address this without requiring you to accept an inadequate settlement:
Medical liens. Many medical providers will treat accident victims on a lien basis, deferring payment until the case resolves. This allows you to receive necessary care without paying out of pocket while the claim is pending.
Medical payments coverage. Your own auto insurance policy may include MedPay or PIP coverage that can pay immediate medical costs regardless of fault, providing a bridge while your claim develops.
Attorney case cost advances. Personal injury attorneys handling cases on contingency typically advance case costs, meaning you do not need to fund the claim’s development out of pocket.
Pre-settlement funding. In some circumstances, third-party litigation funding companies will advance money against a pending personal injury claim. This carries costs and should be discussed with your attorney before pursuing it.
Nevada’s Two-Year Statute of Limitations
One legitimate time pressure in Nevada personal injury cases is the statute of limitations under NRS 11.190(4)(e), which gives you two years from the date of the accident to file suit. However, the solution to this deadline is not to accept a bad settlement quickly — it is to consult with an attorney promptly so the claim is properly preserved and developed within the legal timeline.
Marathon Law Group: Evaluating Settlement Offers in Nevada
If an insurance company has made you a settlement offer and you are not sure whether it is fair, contact Marathon Law Group for a free consultation. We review settlement offers regularly and can tell you whether the amount on the table reflects the real value of your claim. We handle personal injury cases on a contingency fee basis, and we come to you if traveling is difficult. Call us at (702) 522-1808, email mlg@marathonlawgroup.com, or contact us online.
This blog post is for general informational purposes only and does not constitute legal advice. Reading this content does not create an attorney-client relationship. Every case is different. Please consult a licensed Nevada attorney for advice specific to your situation. Prior results do not guarantee a similar outcome.